01
How much does a mortgage broker make on a $500,000 loan?
+
There’s no single figure. Broker pay is set by the lender and the deal, and it changes with the loan type, the province or state, and whether the borrower or the lender pays. Ask the lenders you place with for their current schedule. For SEO, the number to watch is different: how many of your loan and city searches your pages rank on page one for.
02
Is SEO dead or evolving in 2026?
+
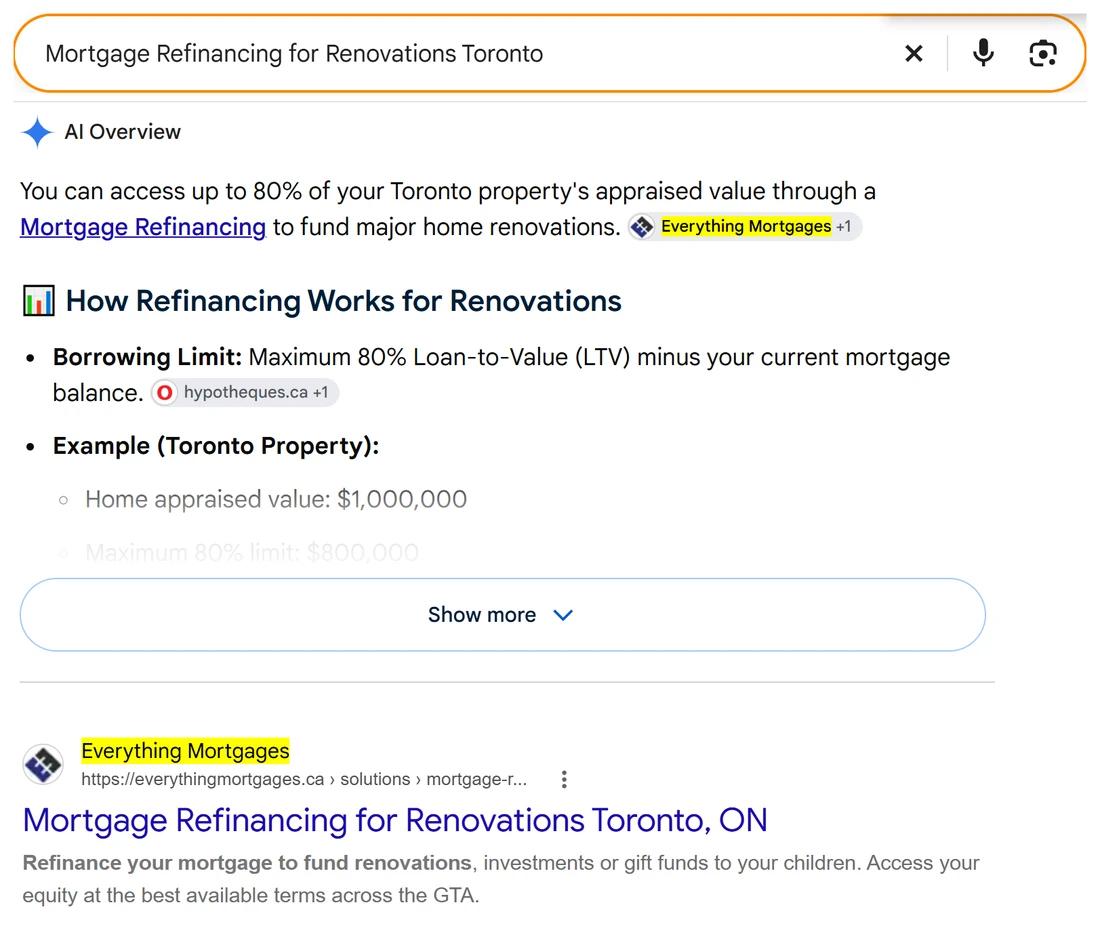
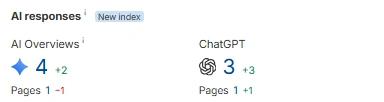
Evolving. Borrowers still search Google for the loan they need, and the same loan pages that rank there now also feed Google Maps and the answers written by Google’s AI and ChatGPT. The work pays off in more places than it used to, not fewer.
03
Will AI replace mortgage brokers?
+
No. Borrowers still need a broker to find the right lender and place the loan. What changes is how they find that broker: they ask AI tools to explain a loan and to name who offers it near them, and those answers name brokers whose pages explain the loan clearly.
04
What is the 3 7 3 rule in mortgage?
+
It’s the timing rule for consumer home loans in the US, refinances included. The lender sends a Loan Estimate within three business days of an application, the borrower can’t close until seven business days after that estimate was sent, and the Closing Disclosure has to reach the borrower at least three business days before closing. Some changes to the rate or the loan restart that last wait. It comes from the US federal disclosure rules, so it doesn’t apply in Canada.
05
Our business comes from realtors and referrals. Why do we need SEO?
+
Keep the referrals. But a referral still ends in a search: the borrower who was given your name looks you up before they get in touch, and if what they find is thin, they keep looking. And the borrower with no referral picks from whoever shows up first.
06
Can a broker really rank above the banks?
+
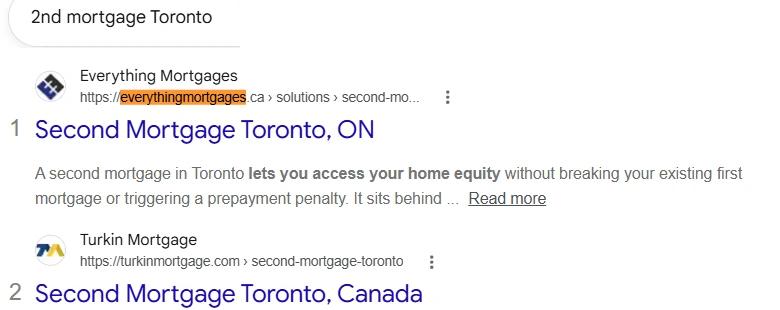
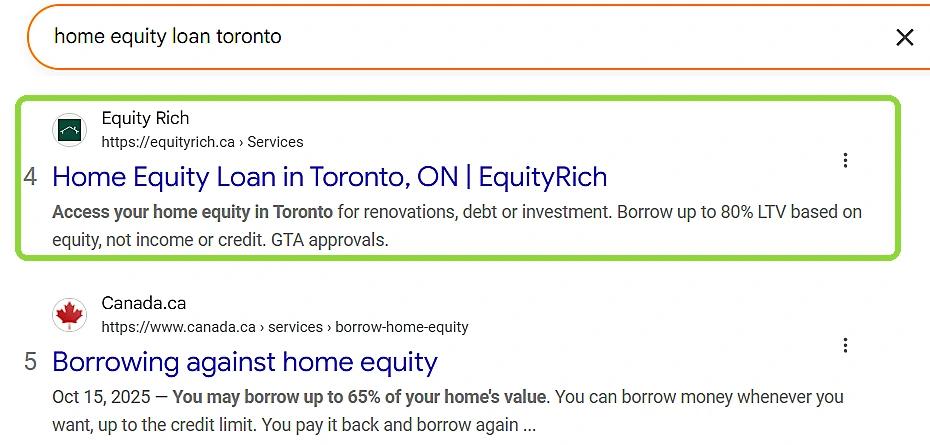
The banks have big websites, but they rarely have one clear page for your product in your city. That’s the gap. In Oct 2026, EquityRich’s home equity loan page was result 4 on Google, directly above the Government of Canada’s own page.
07
Can we list our loan products on our Google listing?
+
No. Google doesn’t allow financial services in the products on a Business Profile. So commercial mortgages, private mortgages and home equity loans each get a page of their own on your website instead, written for the borrower deciding whether to apply.
08
Every page has to pass compliance. Does that slow this down?
+
Tell us what your regulator and your brokerage require, and we write within it. A loan page that’s clear about who qualifies, what it costs and who’s licensed is also the kind of page Google trusts with money searches.
09
Should we add mortgage words or our city to our Google business name?
+
No. Google asks for your real-world name, the one on your sign and your licence. Adding extra words to the name isn’t allowed, and it can get your listing suspended. Your city, loan types and services go in the parts of the listing made for them.
10
How should we ask borrowers for reviews?
+
Ask when they’re happy: the day the loan funds, or when the keys are in their hand. Send them the direct link to your Google review form so it takes one tap. Never pay for a review or offer a rate break in return. Google’s rules don’t allow it, and it removes reviews that break them.
11
How should we reply to a bad review?
+
Briefly and calmly. Thank them, say what you’ll do about it and invite them to talk to your office. Keep rates, income and file details off the review. Borrowers reading it later judge the brokerage by the reply as much as by the review.
12
We’re part of a brokerage network or franchise. Can we still do this?
+
Yes. We work inside the network’s rules for listings, pages and compliance. If the network runs the website, we hand their team the finished pages and a plain list of where each one goes.
13
Should a mortgage broker have a blog?
+
Only if it answers questions borrowers ask: what a second mortgage costs, how a renewal works, what self-employed borrowers need to qualify. A short post like that, linked to the loan page, helps the loan page. Posts written to fill a calendar don’t.
14
Who writes the loan and city pages?
+
We do, from the searches borrowers actually make for each loan and city. You check every detail about rates, terms and who qualifies, so nothing on the page is a promise your brokerage doesn’t keep.
15
Do you put the pages on our website?
+
Yes. We publish them. If someone else manages your website, we hand them the finished pages and a plain list of where each one goes, so it’s copy and paste.
16
What access do you need to our website?
+
Access to your website’s admin area, your Google Business Profile, your Google Search Console and your Google Analytics. If someone else runs your site, we can work through them instead.
17
We already have an SEO agency. How do we switch?
+
We start by reading what’s there: which pages rank, which ones bring visitors and which loans and cities have no page. Nothing that works gets thrown away. You only need to give us access to your website and your Google tools.
18
What happens on the free strategy call?
+
It’s 30 minutes on Google Meet. We look up the loan searches in your cities, the pages you’re missing and who ranks above you. You leave with that list whether you work with us or not.
19
Do you guarantee a #1 ranking?
+
We don’t promise a set position, because Google decides the order. We give two promises in writing, with dates on them, and both are set out in full in the guarantees section on this page.